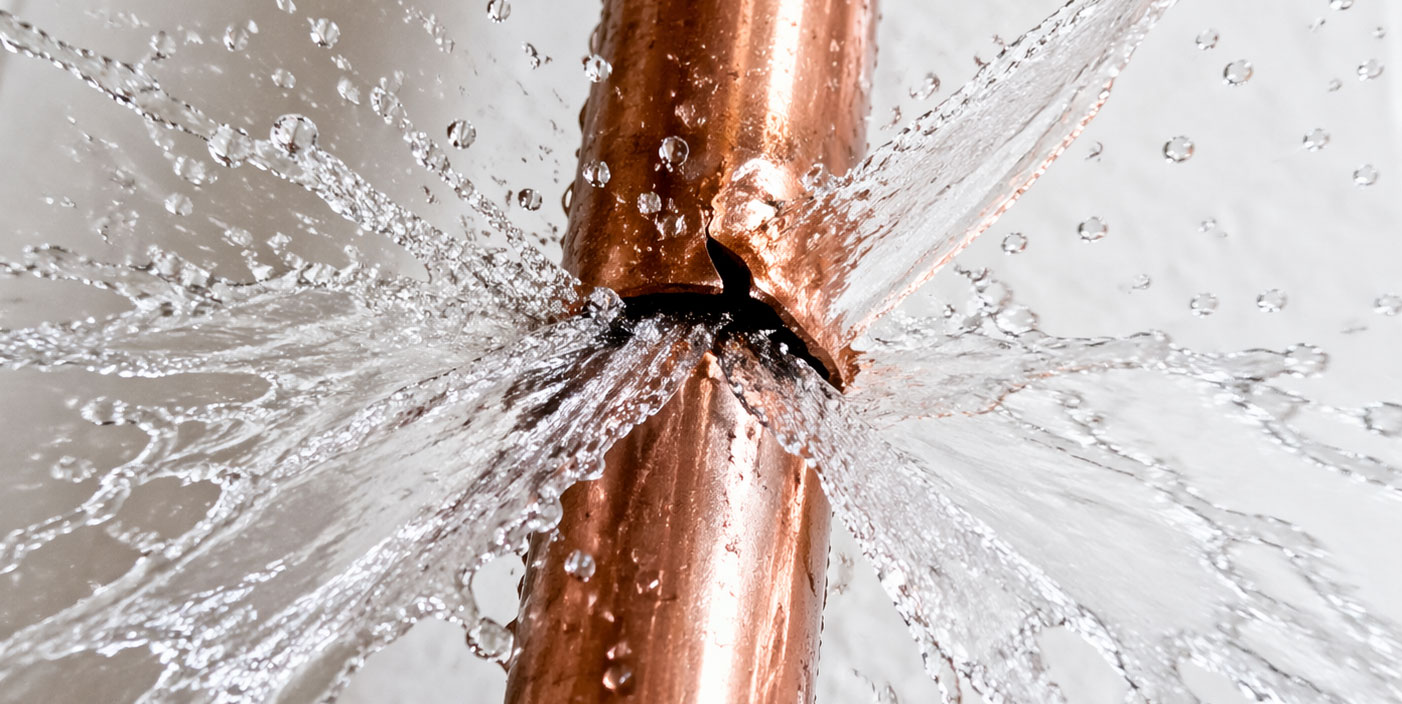
What Actually Happens When an Adjuster Evaluates Water Damage From a Plumbing Failure

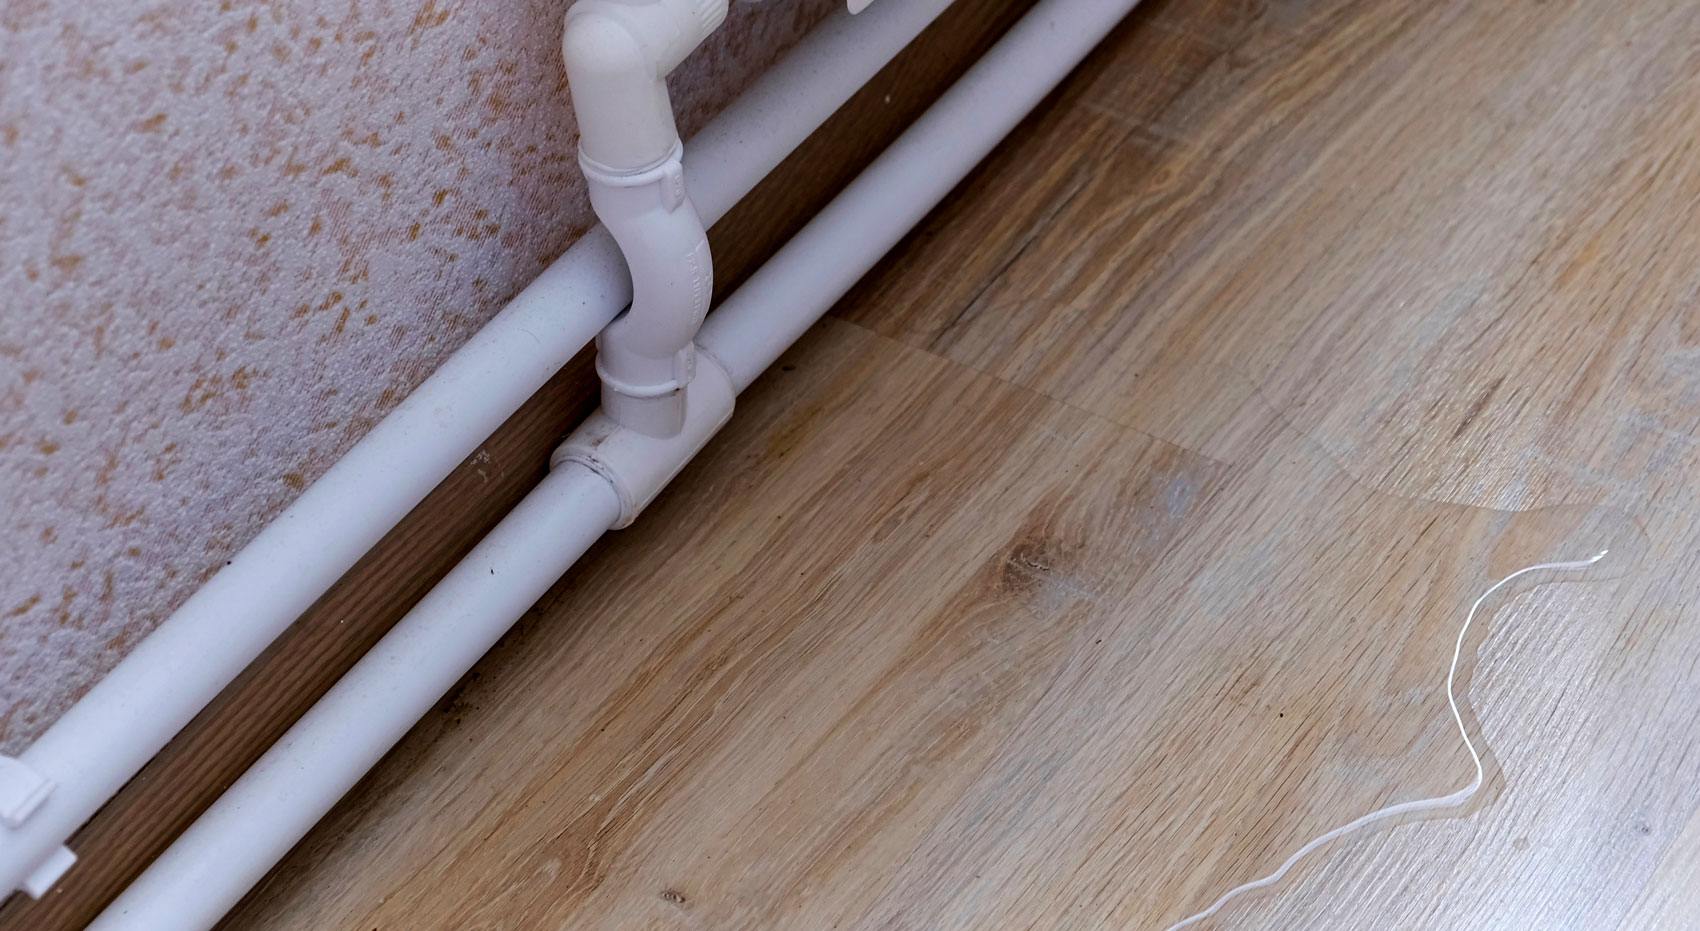
Water damage from a plumbing failure has a way of being both obvious and deeply deceptive at the same time. The wet floors, the soaked drywall, the ruined belongings — those are the parts you can see. But the part that tends to cause the most long-term trouble is everything hiding behind the walls, under the subfloor, and inside the insulation where no one thinks to look.
Continue ReadingWhat Actually Happens When an Adjuster Evaluates Water Damage From a Plumbing Failure

Understanding Depreciation vs. Replacement Cost in Insurance Claims

Understand the critical difference between Replacement Cost Value (RCV) and Actual Cash Value (ACV) in your insurance claim. Learn how depreciation impacts your payout, what "recoverable depreciation" means for your wallet, and how a public adjuster ensures you receive the maximum settlement to rebuild.

Continue ReadingUnderstanding Depreciation vs. Replacement Cost in Insurance Claims

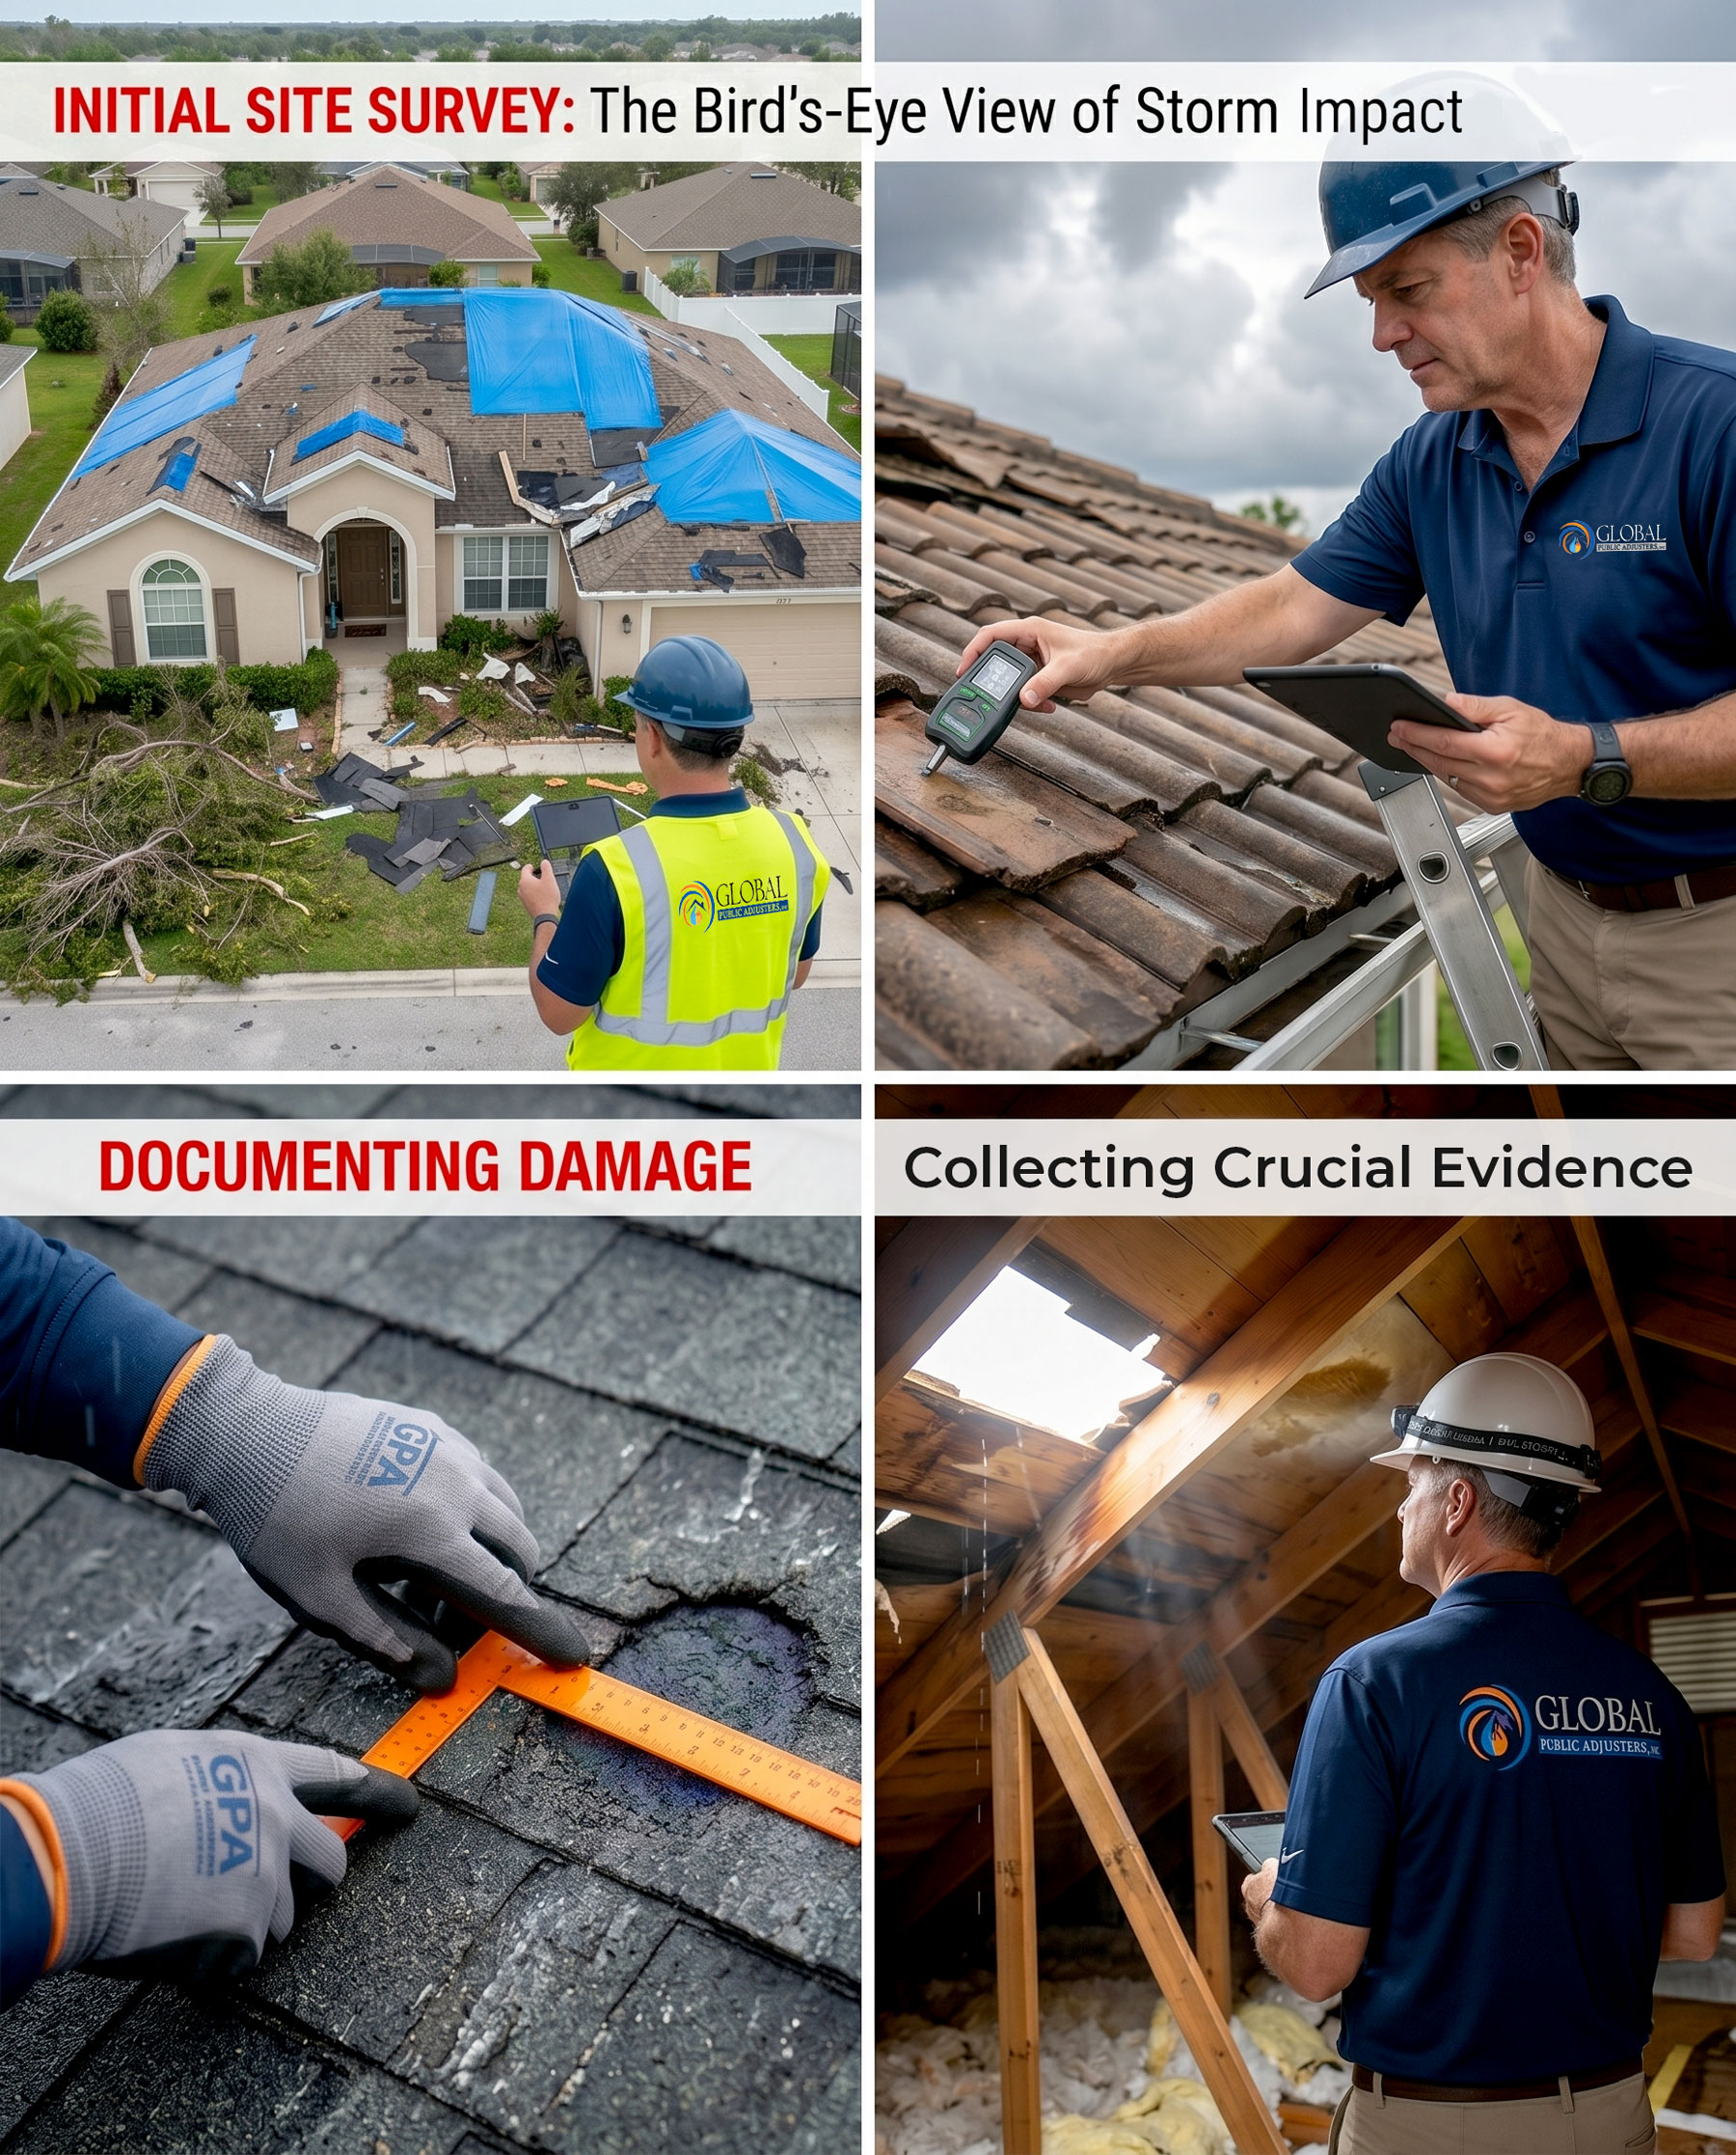
How Adjusters Assess Roof Damage After Florida Storms

Learn how Florida public adjusters assess roof damage after a storm. From identifying subtle shingle lift to documenting interior water stains, we ensure no hidden damage is overlooked by your insurance carrier. Get the full value of your claim with a professional, 'inside-out' inspection.

Continue ReadingHow Adjusters Assess Roof Damage After Florida Storms

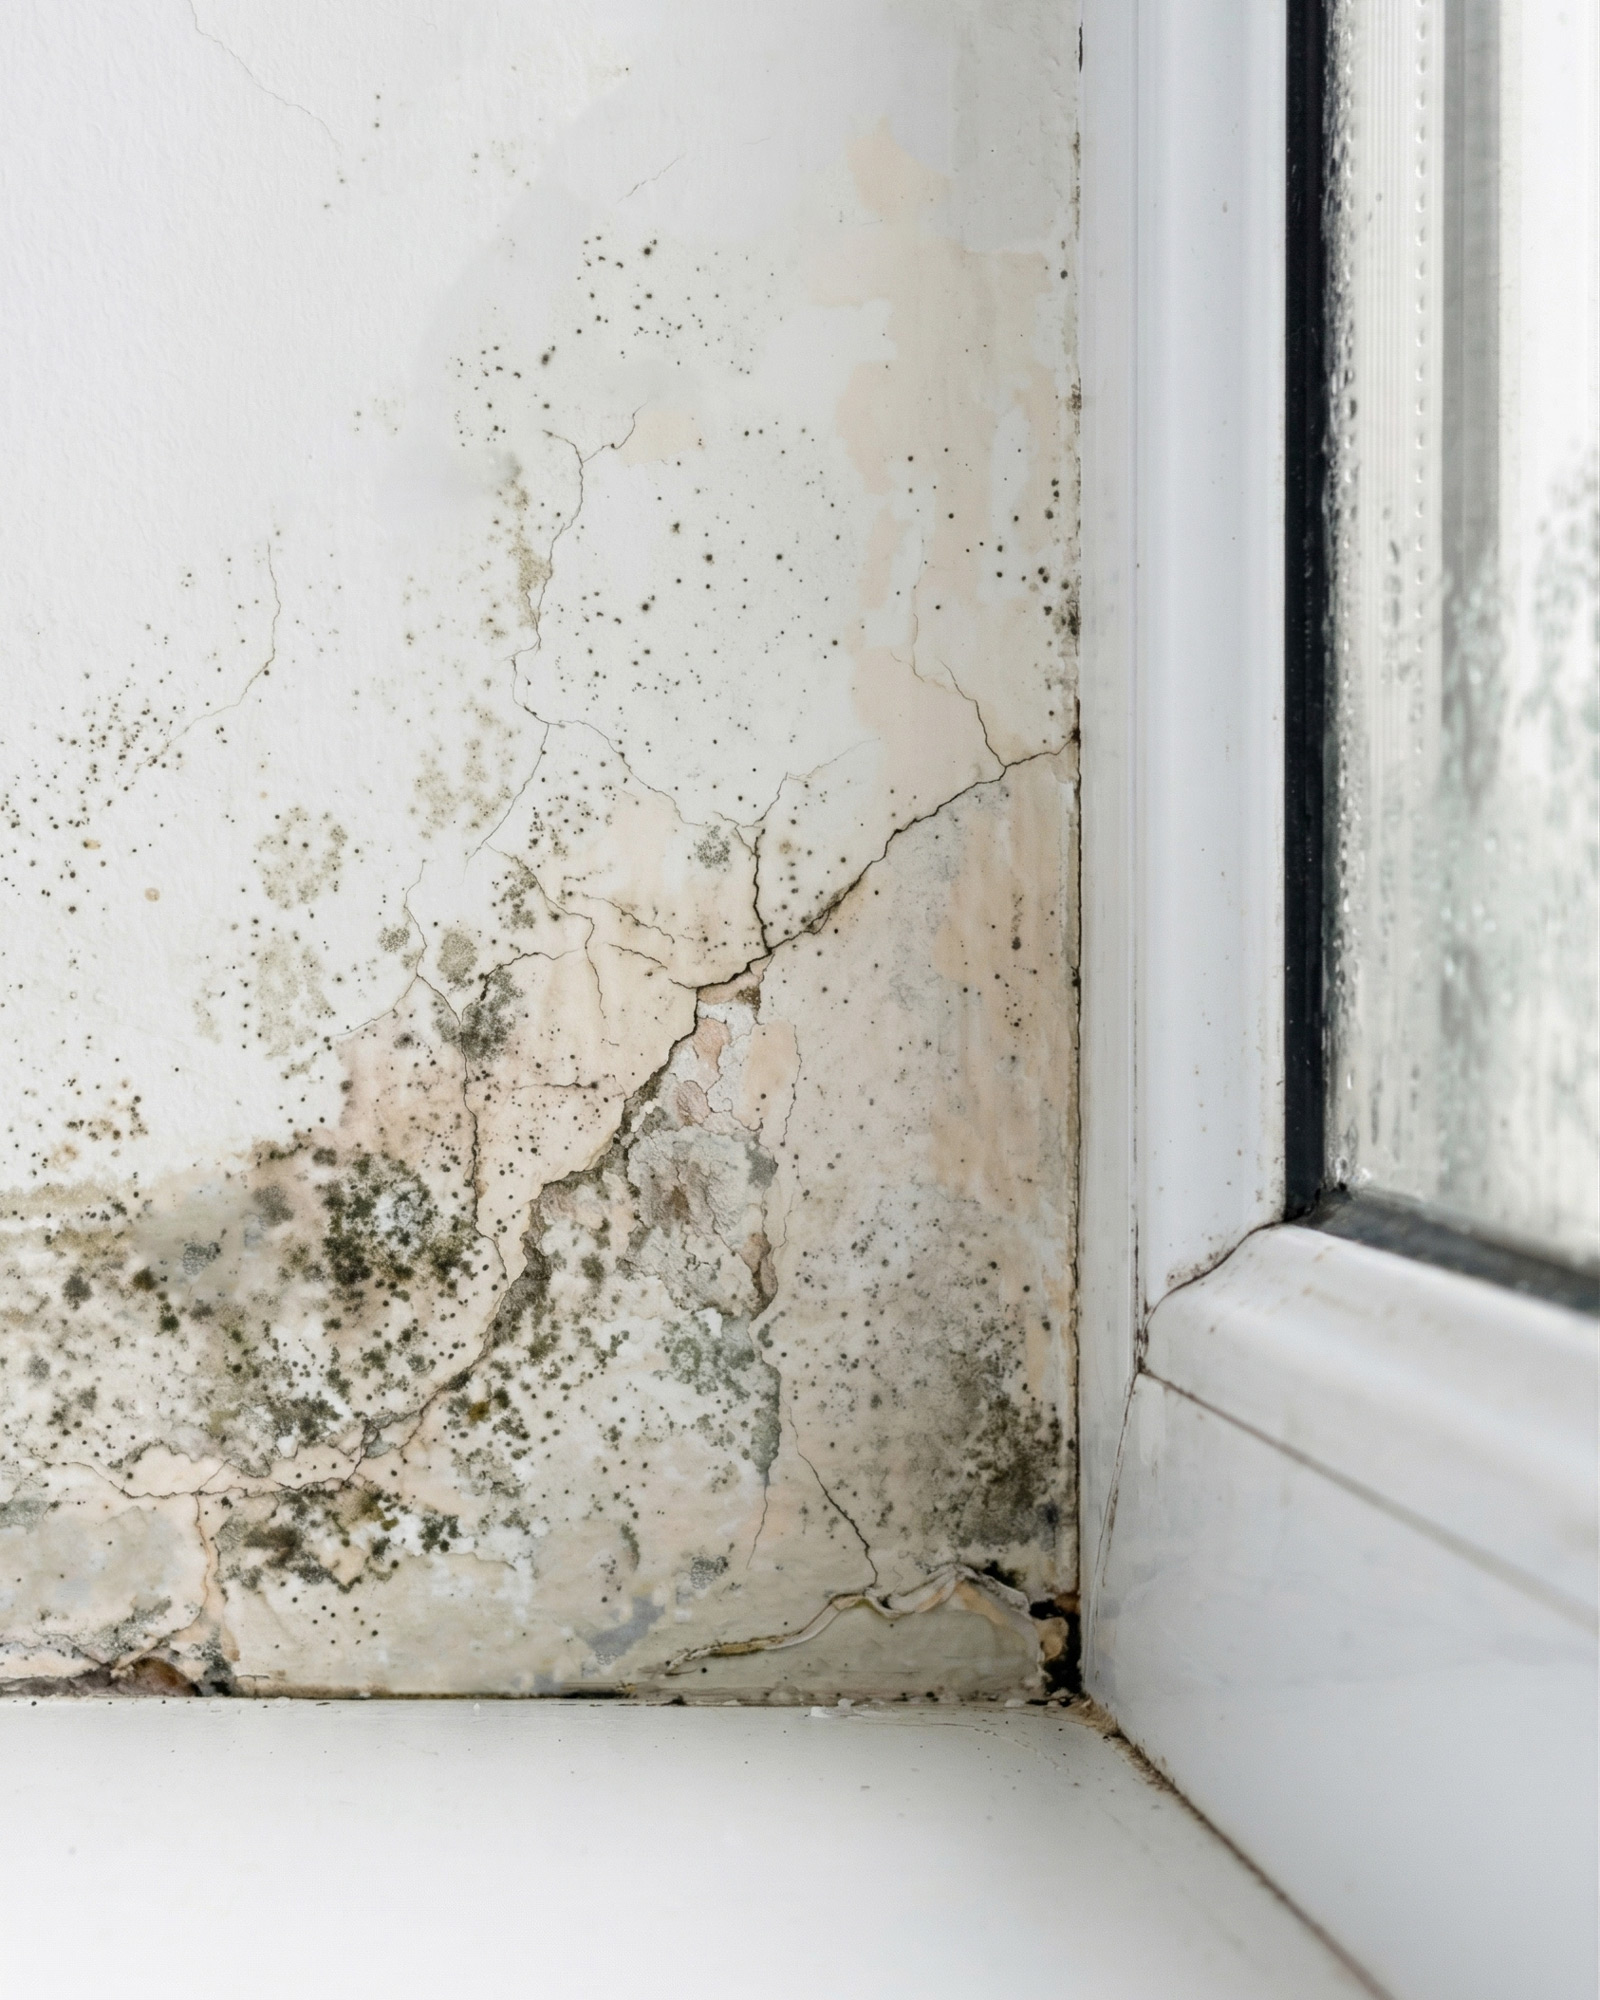
How Adjusters Evaluate Mold Damage

Mold damage sits in an uncomfortable middle ground for many homeowners. It's not always visible, it's not always straightforward to trace back to a specific cause, and insurers don't always approach it with the same clarity they bring to more obvious losses. Whether a mold claim gets approved, and for what amount, often comes down to how thoroughly the damage is documented and how precisely its origin point is established.

Continue ReadingHow Adjusters Evaluate Mold Damage

Understanding Business Interruption Claims

When a fire, flood, or storm damages a business property, the physical loss is visible and immediate. What's harder to quantify — but often just as financially significant — is what happens while the doors are closed. Revenue stops. Fixed costs don't. And the longer the recovery takes, the wider that gap grows.

Continue ReadingUnderstanding Business Interruption Claims