
Why More Florida Homeowners Are Getting Denied for “Wear and Tear” Claims
When storm damage gets mislabeled, you deserve an advocate who knows the difference
There is a phrase Florida homeowners are hearing more and more often, and it usually arrives in a denial letter. Wear and tear. Insurance carriers are increasingly using this label to deny claims that homeowners believe, often correctly, stem from storm damage. It is one of the most frustrating experiences a policyholder can face. You pay your premiums for years, a storm rolls through, your roof starts leaking, and the response from your insurer is essentially that your house was just getting old anyway. At Global Public Adjusters, we see this trend weekly, and we want you to know something important about it. A denial letter is not the final word, and you do not have to accept it alone.
What These Denials Look Like
The line between storm-related damage and normal aging is genuinely blurry, and carriers know it. That gray area is where questionable denials live. We regularly see cases like these:
- Roof leaks dismissed as aging shingles, even when the leaks began right after a named storm
- Cracked tiles attributed to settling rather than wind or debris impact
- Water intrusion blamed on poor maintenance instead of storm-created openings
Individually, each explanation might sound plausible. That is exactly what makes them effective. A homeowner without construction expertise or claims experience has a hard time pushing back, and many simply give up. Insurers count on that.
How Global Public Adjusters Fights Back for You
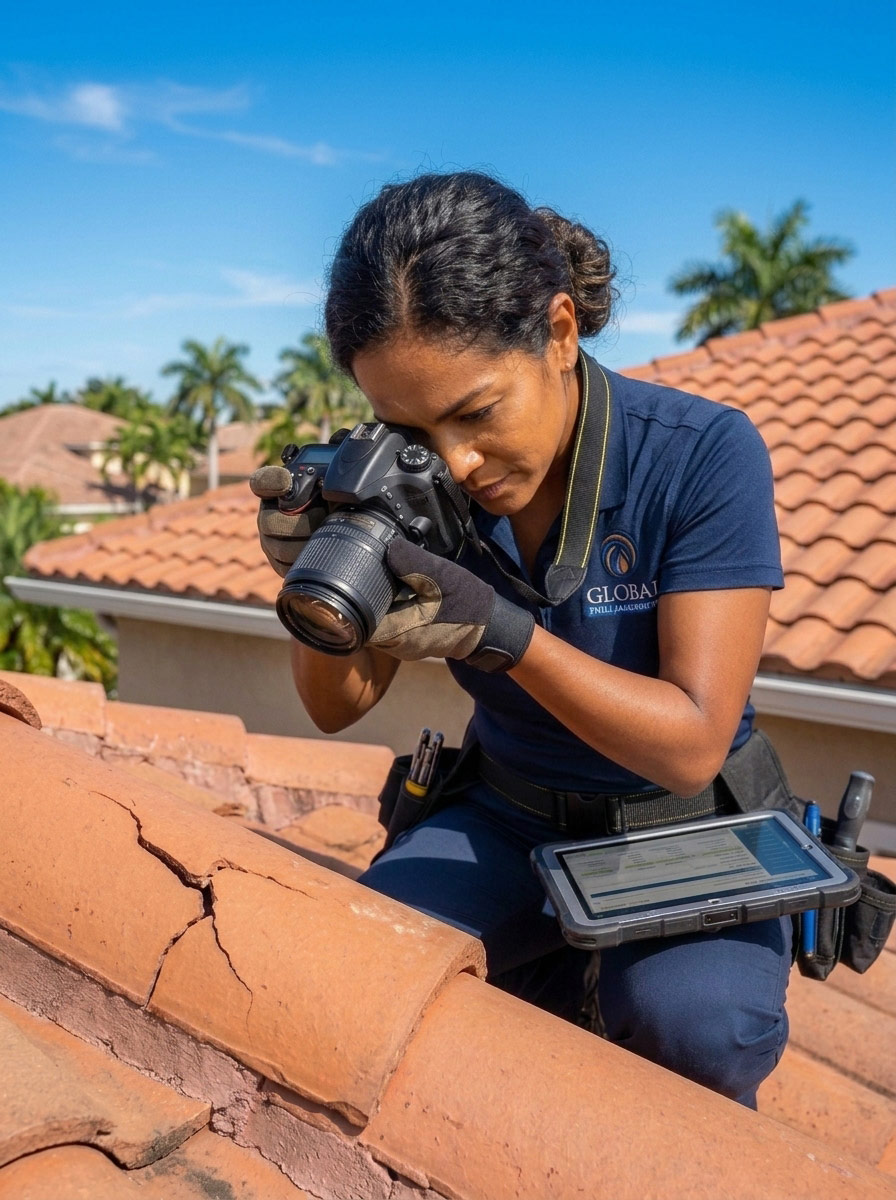
This is where having a champion in your corner changes the entire equation. Our public adjusters work exclusively for policyholders, never for insurance companies, and we know exactly how to challenge a wear and tear denial. We gather physical evidence from your property, documenting damage patterns that distinguish storm impact from gradual aging. We compare timelines, connecting the onset of damage to specific weather events with dates, storm data, and inspection findings. And we dig into your policy language, because coverage often turns on definitions and exclusions that carriers interpret in their own favor.
Wind-lifted shingles do not look like sun-worn shingles when you know what to look for. Impact cracks do not behave like settling cracks. These distinctions are our profession, and we put that expertise to work making sure you are not unfairly penalized for damage a storm actually caused.
How Homeowners Can Protect Themselves Now
The strongest claims are built before damage ever happens. Homeowners can put themselves in a far better position by documenting their property’s condition with dated photos and periodic inspection reports, and by keeping maintenance records that show proactive care over time. When you can prove your roof was sound in May, an insurer has a much harder time claiming that your September storm damage was really years of neglect. Think of it as building your case in advance, quietly and inexpensively, so the evidence is ready if you ever need it.
You Deserve a Fair Evaluation
Understanding the difference between wear and tear and storm damage is essential in Florida’s current insurance climate, but you should not have to become an expert to get what your policy promises. That is our job. Global Public Adjusters brings the documentation, the construction knowledge, and the negotiating experience to ensure your claim is evaluated fairly and completely. When a carrier tries to shrink your storm claim into a maintenance problem, we push back with evidence, and we do not stop until your claim gets the honest evaluation you paid for.
